Debt-to-income: the ratio that caps your loan
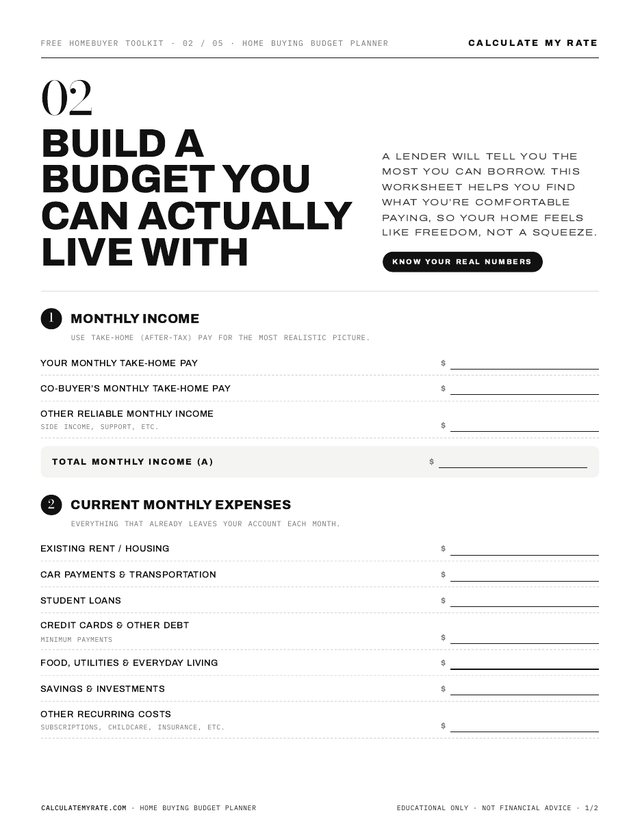
Your debt-to-income ratio (DTI) is the share of your gross monthly income that goes to debt payments — including your future mortgage. It's one of the first things a lender checks, because it signals whether you can comfortably carry the loan.
The CFPB notes that lenders generally look hardest at borrowers whose total DTI stays at or below the low-to-mid 40s percent; many programs treat 43% as a common upper benchmark, though it varies by loan type and your overall profile.
The practical takeaway: paying down a car loan or credit card before you apply can lift the loan amount you qualify for — sometimes more than a higher income would. Lowering your DTI is one of the few levers fully in your control.
Source: CFPB guidance on debt-to-income ratio and qualifying for a mortgage.
Move your credit score and down payment and watch your rate update.