How your credit score sets your rate
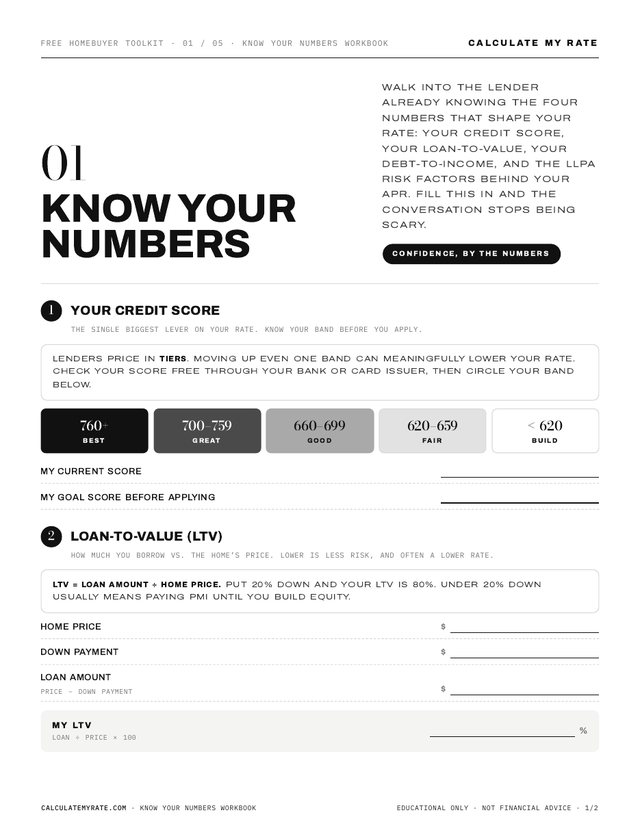
Your credit score is the single biggest input to the rate you're offered. Lenders price in tiers, so moving up even one band can change your pricing meaningfully.
FICO scores run from 300 to 850, and conventional pricing generally improves in steps as you climb (740+, 760+, and so on). Each higher tier carries a smaller risk-based add-on — which is why a jump from 680 to 760 can erase most of your LLPA and save thousands on a typical loan.
What actually moves the score: payment history is about 35% of a FICO score and amounts owed (your credit utilization) is about 30% — the two largest factors by far. Keep balances low and never miss a due date.
Source: FICO published score composition; Consumer Financial Protection Bureau (CFPB) guidance on credit scores and mortgage pricing.
Move your credit score and down payment and watch your rate update.