PMI vs MIP: they sound the same, but one can cost you for decades
PMI drops off at 20% equity; FHA's MIP often lasts the life of the loan. Learn the difference between conventional and FHA mortgage insurance — and how to get rid of each.
Both are mortgage insurance. But one falls off your payment automatically — and the other can stick around for the life of your loan. Here's the difference, and how to get rid of each.
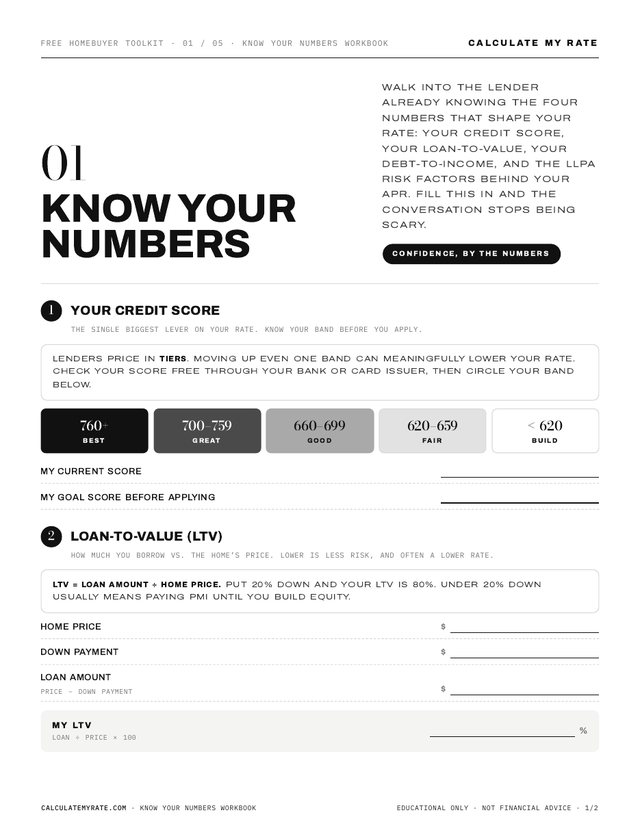
When you buy a home with less than 20% down, your lender adds mortgage insurance to your payment. It protects the lender — not you — if you stop paying. Almost every low-down-payment buyer pays it, and most people never learn that the two main types behave completely differently.
The type you get depends entirely on your loan: PMI on conventional loans, MIP on FHA loans.
PMI — conventional, and it goes away
PMI (Private Mortgage Insurance) applies to conventional loans when you put down less than 20%. The good news: it's temporary. As you pay down your balance and build equity, PMI cancels.
You can request cancellation once you reach 20% equity, and by federal law (the Homeowners Protection Act) your servicer must automatically remove it at 22% equity, as long as you're current on payments. Once it's gone, it's gone — and your monthly payment drops.
MIP — FHA, and it often doesn't
MIP (Mortgage Insurance Premium) applies to FHA loans — and here's the catch most buyers don't see coming: with the typical FHA down payment (less than 10%), MIP lasts the entire life of the loan. It doesn't fall off at 20% or 22% equity the way PMI does.
FHA loans also charge an upfront MIP at closing on top of the monthly premium. So while FHA is fantastic for getting you into a home with a low down payment and flexible credit, it can quietly cost more the longer you stay.
The smart play: FHA gets you in, then refinance out
This is the move a lot of homeowners don't realize they can make. Use an FHA loan to buy, then — once you've built around 20% equity — refinance into a conventional loan. A conventional loan at 20% equity has no PMI at all, so the refinance can erase your mortgage insurance entirely.
Run the numbers first: weigh your new rate and closing costs against the MIP you'd shed. If you'll stay in the home past the break-even point, dropping MIP can save you thousands.
Before you pick a loan
Compare the total cost of PMI vs MIP — not just the headline rate — when you're choosing between a conventional and an FHA loan. The right answer depends on your credit, your down payment, and how long you plan to stay. A few minutes of math now can save you years of unnecessary insurance later.
Sources: Consumer Financial Protection Bureau (CFPB) guidance on private mortgage insurance; Homeowners Protection Act of 1998 (PMI cancellation & automatic termination); U.S. Department of Housing and Urban Development (HUD) / FHA mortgage insurance premium guidelines.
Move your credit score and down payment and watch your rate update.