PMI doesn't have to be forever
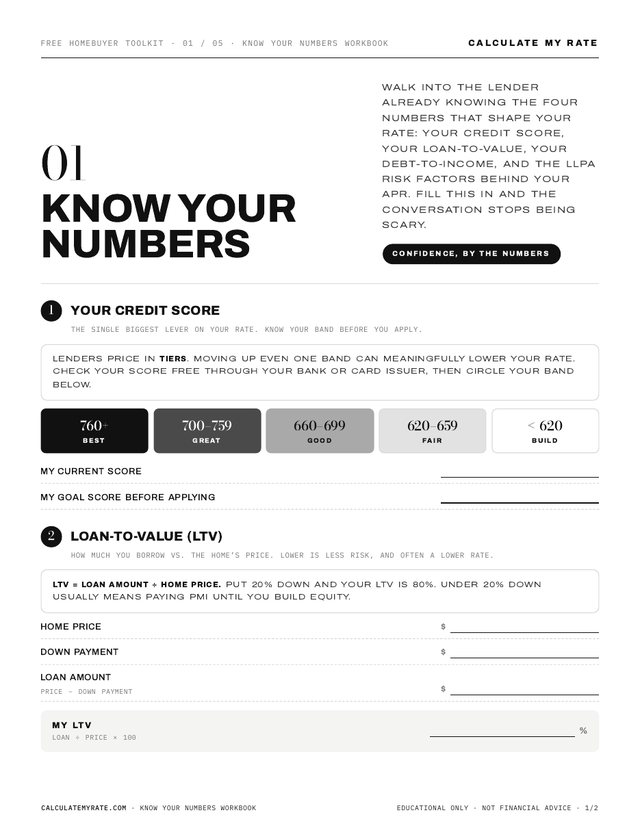
Private Mortgage Insurance (PMI) is required on most conventional loans when you put down less than 20%. It protects the lender — not you — if you stop paying. But it's not permanent, and federal law gives you the right to get rid of it.
Under the Homeowners Protection Act:
- You can request cancellation once your loan balance reaches 80% of the home's original value.
- The lender must automatically terminate PMI when you reach 78% — no request needed.
- If your home has appreciated, a new appraisal can get you to 20% equity faster than the amortization schedule alone.
Use the PMI calculator to find the exact month your balance crosses those thresholds — then put the cancellation request in writing.
See it on your own numbers
Try the calculator Move your credit score and down payment and watch your rate update.